When phone calls go unanswered and letters pile up unread, a field agent visit can be the most direct way to break a payment deadlock. But sending someone to knock on a debtor’s door is not a free-for-all. In Australia, face-to-face debt collection is tightly regulated, and agents who step outside those boundaries expose themselves and their clients to serious legal risk.
This guide covers what field agents can and cannot do, what debtors can expect during a visit, and how to keep the entire process on the right side of Australian law.
What Is Face-to-Face Debt Collection?
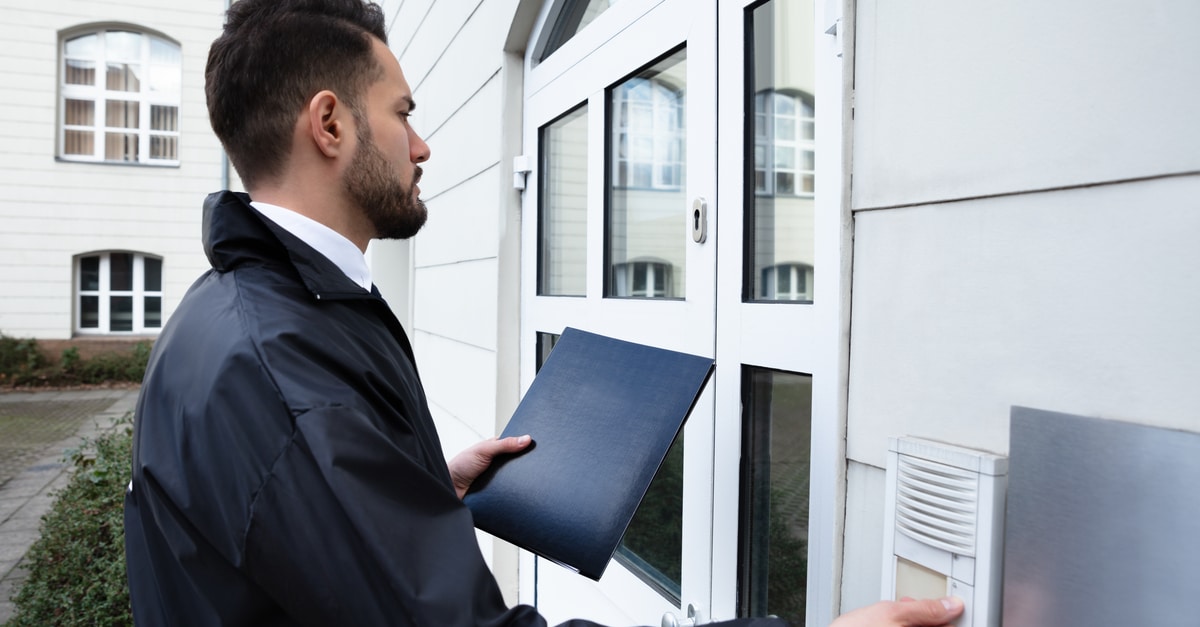
Face-to-face debt collection involves a trained field agent visiting a debtor’s home or business in person to recover an outstanding amount. Unlike a letter or a phone call, a direct visit creates a real-time conversation where payment options can be discussed, disputes raised, and arrangements reached on the spot.
These visits are particularly useful when other contact methods have failed, or when a creditor needs to confirm a debtor’s current circumstances before deciding on next steps. The in-person approach comes with clear rules around timing, conduct, and identification that every agent must follow under Australian law.
The Legal Framework Governing Field Agent Visits
Australia has a solid framework for regulating debt collection conduct. The Australian Consumer Law (ACL) sits at the centre of it, setting out protections against harassment, coercion, and misleading conduct. The ACCC and ASIC debt collection guidelines build on this by providing practical rules on contact frequency, visit timing, and how agents must communicate with debtors.
Together, these rules give both creditors and debtors a clear picture of what is acceptable. For a more detailed breakdown of how these frameworks operate in practice, the debt collection guidelines and legal collection process in Australia is worth reading before you engage a field agent.
Who Are Field Agents and What Do They Actually Do?
Field agents, also called mercantile agents, are licensed professionals authorised to visit debtors in person on behalf of a creditor. Their job is to make contact, assess the debtor’s situation, and work toward a resolution. That might mean agreeing on a structured repayment arrangement, documenting a dispute, or confirming a debtor’s address for further legal steps.
In Victoria and several other states, mercantile agents must hold a current licence to operate. Unlicensed agents acting in this capacity face penalties, and any agreements they reach can be challenged. This is one reason why working with a properly credentialled agency matters from the start.
Field Agent Visit Rules: What the Guidelines Actually Say
Permitted Hours
Field agents can visit a debtor’s home or business only during reasonable hours. Under the ACCC and ASIC guidelines, that generally means weekdays between 7:30 am and 9:00 pm, and weekends between 9:00 am and 9:00 pm. Visits on public holidays should be avoided unless the debtor has specifically agreed to them.
Turning up at 6:30 am or knocking on a door at 10 pm is not just poor form. It is a direct breach of the guidelines and can result in a formal complaint.
Frequency of Contact
Even in-person visits are subject to frequency limits. Agents cannot make repeated visits in a short timeframe in a way that amounts to harassment. The ACCC guidelines apply across all contact channels: phone, letter, and face-to-face visits combined. Excessive contact is treated as harassment and can lead to fines, complaints, and in serious cases, legal action against the creditor.
Identification Requirements
Every field agent attending a property must clearly identify themselves before any discussion takes place. At minimum, they should present a company identification card and, where required by state law, their mercantile agent licence number. Debtors are entitled to ask for this information before engaging, and any legitimate agent will comply without hesitation.
Fraud is a real consideration here. Door-to-door debt collection scams do occur in Australia, and one common red flag is an agent who cannot or will not produce proper credentials.
Mercantile Agent Rights: What They Can and Cannot Do
Mercantile agents have the right to attend a debtor’s property and request a conversation. That is broadly where their authority ends at the front door. They cannot enter a home or business without the occupant’s permission unless they hold a valid court order. They cannot use threats, intimidation, or coercive pressure of any kind. They cannot misrepresent the amount owed or overstate the legal consequences of non-payment.
Agents must also avoid discussing the debt with anyone other than the debtor. If a family member, housemate, or neighbour answers the door, the agent should not reveal the nature of the visit. Doing so breaches the debtor’s privacy rights and can constitute unconscionable conduct under the ACL.
If a debtor clearly asks an agent to leave and refuses to engage, the agent must comply. Remaining on private property against the occupant’s wishes can constitute trespass.
Debtor Privacy Protections During Field Visits
Privacy obligations carry real weight in field-based debt recovery. The Privacy Act 1988 requires agents to handle personal information with care, use it only for the purpose for which it was collected, and store it securely. Any notes taken during a site visit, including personal circumstances disclosed by the debtor must be treated accordingly.
Announcing the purpose of a visit in earshot of neighbours, or leaving written notices that reveal the nature of the call, are both breaches of these obligations. Debtors who believe their privacy has been compromised during a field visit should document the incident and raise a formal complaint.
How Field Agents Should Conduct Themselves
Professional conduct is not optional. The field agent code of conduct requires agents to approach every visit with honesty, fairness, and respect. That means listening without interrupting, providing accurate information about the debt, and keeping the tone measured even when the conversation becomes difficult.
Good conduct also produces better results. Debtors who feel they are being treated fairly are more willing to engage, disclose their circumstances, and commit to a repayment arrangement. Agents who pressure or mislead tend to entrench resistance and generate complaints that slow everything down. For more on how professional agents build productive outcomes, how collections agents maintain good working relationships with debtors covers this well.
Negotiating at the Door: What Debtors Should Know
A field visit does not have to end in confrontation. Debtors have every right to raise a dispute, ask for more time, or propose a repayment arrangement during the visit. Agents are trained to handle these conversations and should be prepared to discuss options, not just demand immediate payment.
If a debtor believes the debt amount is incorrect, they should say so clearly and ask the agent to note the dispute in their records. Any agreement reached during the visit, a payment plan, a follow-up call, or a promise to provide documentation, should be confirmed in writing as soon as possible by both parties. A verbal agreement made at the door is easily misremembered by either side. For a full guide on structuring these discussions, negotiating debt payment terms with your debtors is a practical starting point.
Documenting the Visit: Why It Matters
Thorough records are non-negotiable. Field agents must document every visit, recording the date and time, who was present, what was discussed, any agreements reached, and the identification provided by the debtor. This documentation protects the agent against future complaints and gives the creditor a clear picture of the recovery process to date.
Debtors should keep their own notes as well. If an agent makes a statement that seems incorrect, about the amount owed, legal proceedings, or their own authority, write it down immediately after the visit. That record could be important if a formal dispute arises.
Harassment and Coercion: Where Australian Law Draws the Line
Australia takes a firm position on harassment in debt collection. The ACL and the ACCC/ASIC guidelines prohibit threats of physical harm, false statements about legal proceedings, abusive language, contact designed to intimidate, and pressure tactics that amount to unconscionable conduct. An agent who visits repeatedly within a short period, attends at unreasonable hours, or makes threatening statements is operating outside the law, full stop.
Debtors who experience this kind of treatment during a doorstep visit should document everything and report it to the ACCC or their state’s fair trading authority. Agents found in breach face licence suspension, fines, and civil liability.
Ethical Debt Recovery in Practice
Professional conduct during field visits matters for reasons beyond compliance. Agents who act with integrity recover more debt. Debtors who feel respected are more willing to engage honestly, disclose their real financial position, and follow through on commitments. Agents who use aggressive or misleading tactics push debtors toward avoidance, formal complaints, and protracted disputes that cost everyone time and money.
Businesses that want to recover what they are owed without damaging client relationships or their own reputation should treat ethical debt collection practices as a core part of their recovery strategy, not an afterthought.
Getting the Process Right
Face-to-face debt recovery is a legitimate and often effective tool. When it is done properly, by licensed agents, within permitted hours, with clear identification, and with a professional approach throughout then it gives creditors a genuine chance of resolving accounts that have stalled through other channels.
If your business is dealing with outstanding debts and you need an authorised, compliant field agent service, Bell Mercantile’s debt collection and recovery services are built for exactly this. Call us on +61 3 9596 9311 or reach out through our contact us page to find out how we can help.
FAQs
Are debt collectors allowed to visit my home in Australia?
Yes, debt collectors and field agents are legally permitted to visit your home, but it must be as a last resort. Under Australian guidelines, they should only visit if they have been unable to contact you via phone or mail or if you have specifically requested a face-to-face meeting.
What time of day can a field agent visit my property?
In Australia, face-to-face debt collection visits must only occur between 9:00 am and 9:00 pm. This applies to both weekdays and weekends; however, visits are not recommended on national public holidays.
Can a debt collector enter my house without permission?
No, a field agent has no legal right to enter your home without your express invitation. If they enter your property or home without your consent, they may be committing trespass under Australian law.
Do I have to speak to a field agent if they knock on my door?
No, you are not legally obligated to speak with a field agent. You can choose to communicate with the debt collection agency via written correspondence or over the phone instead, and you can ask the agent to leave your property immediately.
What should I do if a field agent refuses to leave?
If you ask a field agent to leave your property and they refuse, they are trespassing. You should firmly reiterate your request and, if you feel unsafe or they remain on the premises, you should contact the police.
Can a field agent visit me at my workplace?
Visits to a workplace are strictly regulated and should only happen if the agent has no other way to contact you or if you work from home. They must not cause a disturbance or reveal the nature of their visit to your colleagues or employer.
Does a field agent have the power to seize my furniture or car?
No, ordinary debt collectors and field agents in Australia cannot seize your goods or property. Only a court-authorised sheriff or bailiff with a specific warrant or writ has the legal power to repossess items to satisfy a debt.
How often can a debt collector visit me in person?
Face-to-face contact is usually limited to once a month unless there is a very specific reason for more frequent visits. Australian guidelines emphasise that contact should not be excessive or used as a tactic to harass the debtor.
What identification should an Australian field agent carry?
An agent must carry and show you official identification that includes their full name, the name of the agency they represent, and, where applicable, their mercantile agent licence details.
Can a debt collector tell my neighbours about my debt?
No, Australian privacy laws and debt collection guidelines strictly prohibit agents from disclosing your debt to third parties, including neighbours, friends, or family members. They must remain discreet during a home visit.
Are field agents allowed to use physical force?
Absolutely not. The use of physical force, coercion, or any form of intimidation is illegal under the Australian Consumer Law. Any agent using force should be reported to the police and the ACCC.
What is the difference between a field agent and a bailiff?
A field agent is a private representative of a collection agency used for contact and negotiation. A bailiff (or sheriff) is a court official with the legal authority to enforce court orders, such as seizing property.
Can a field agent demand an immediate cash payment at my door?
While they can ask for payment, you are not required to pay them in cash on the spot. It is often safer to organise a bank transfer or pay the agency directly through official channels to ensure you receive a proper receipt.
What laws govern debt collection visits in Australia?
The primary regulations are found in the ASIC-ACCC Debt Collection Guideline, the Australian Consumer Law, and the National Consumer Credit Protection Act. These ensure all collection activity is conducted fairly and without harassment.
Can a field agent visit if I have a financial counsellor representing me?
If you have notified the agency that a financial counsellor or solicitor is representing you, the field agent must generally stop contacting you directly and deal with your representative instead.
What happens if a field agent uses abusive language?
Using abusive, offensive, or demeaning language is a breach of Australian debt collection guidelines. You should document the encounter and lodge a formal complaint with the agency’s internal dispute resolution team or AFCA.
Can I be arrested for not paying a debt when an agent visits?
No, in Australia, you cannot be arrested or sent to gaol for failing to pay a civil debt. Any agent who threatens you with arrest or criminal charges is acting illegally and misleading you.
Do field agents need a licence in Australia?
Licencing requirements for mercantile agents vary by state and territory. For example, in New South Wales and Queensland, agents must meet specific criteria and hold the relevant licences to perform field calls.
Can a field agent take photos of my house or assets?
While they might take a photo of the property to prove they visited, they cannot enter your home to photograph your internal assets or belongings without your permission, as they have no seizure powers.
What should I record during a face-to-face visit?
It is wise to record the date, time, the agent’s name, their company, and a summary of the conversation. This documentation is essential if you need to lodge a complaint later regarding their behaviour.
Can a debt collector visit me if the debt is statute-barred?
If a debt is statute-barred (usually after six years of no payment or contact in most states), it cannot be legally enforced through the courts. While they might still try to contact you, they must not mislead you about their right to sue.
What is unconscionable conduct during a home visit?
This refers to an agent taking unfair advantage of a person’s vulnerability, such as a language barrier, illness, or age. Australian law provides heavy penalties for agencies that engage in unconscionable conduct.
Can I dispute the debt with the agent at the door?
Yes, you can inform the agent that you dispute the debt. Once a debt is formally disputed, the agency should generally pause collection activity while they investigate your claims and provide proof of the debt.
Who can I complain to about a rogue field agent?
You should first complain to the debt collection agency itself. If the issue is not resolved, you can escalate it to the Australian Financial Complaints Authority (AFCA), the ACCC, or your state’s consumer protection agency.
Can a field agent suggest I use my superannuation to pay a debt?
Field agents should not pressure you to access your superannuation early or take out further credit to pay an existing debt. This is considered inappropriate conduct under Australian financial hardship guidelines.